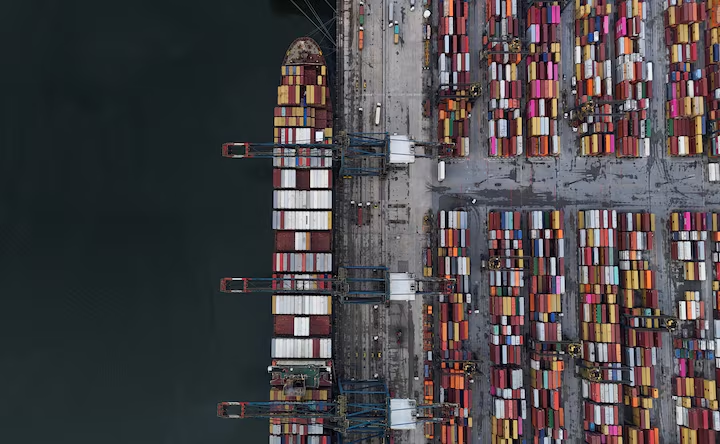
Ocean shipping rates have plunged to their lowest levels since January 2024, raising concerns over profitability for major carriers such as Maersk and Hapag-Lloyd. The decline follows a slowdown in global shipping demand, triggered in part by a series of new trade tariffs imposed by U.S. President Donald Trump earlier this year.
The Drewry World Container Index (WCI) — which tracks the off-contract “spot” rate for transporting a 40-foot container across major trade routes — fell to $1,669 per container as of Thursday, marking a 20-month low. The rate for shipments from Shanghai to Los Angeles, the world’s busiest container route, tumbled 58% year-on-year to $2,196, Drewry data showed.
According to Jefferies ocean shipping analyst Omar Nokta, both rates are now below the estimated $2,200 per-container break-even level for leading carriers such as Maersk and Hapag-Lloyd.
“Rates have fallen below leading-cost operators’ break-even for the first time since late 2023,” Nokta said.
Maersk declined to comment on its break-even figures, while Hapag-Lloyd did not immediately respond to requests for comment.
**Spot Market Weakens as Customers Regain Leverage**
Approximately half of all containerized cargo moves through the spot market, a share that tends to rise when spot rates dip below long-term contract rates.
“With the current drop in spot rates, the gap between spot and contract prices is narrowing, especially on key East–West trade routes,” said Hind Chitty, Senior Manager at Drewry Supply Chain Advisors.
The spot rate for the Shanghai–New York route has also fallen 46% to $3,200, according to Drewry.
Ocean shipping, which carries around 80% of global trade, is widely viewed as a key barometer of global economic health. The United States remains the world’s largest importer of containerized goods, with major retailers such as Walmart, Target, and Home Depot having front-loaded imports of holiday merchandise earlier this year to avoid the impact of Trump’s tariffs. This early “peak season” has, however, softened demand for the remainder of the year.
Some industry analysts warn that inflationary pressures from tariffs could further dampen U.S. consumer spending, prompting retailers — who account for roughly half of all container volumes — to scale back future shipments, adding more downward pressure on freight rates.
**Oversupply Adds to Market Strain**
Adding to the challenges, major carriers including MSC, Maersk, Hapag-Lloyd, and Cosco are taking delivery of new container vessels, increasing capacity in an already oversupplied market.
Supply chain consultancy Sea-Intelligence warned that the industry is heading toward a cyclical overcapacity peak by 2027, comparable to the 2016 slump when carriers slashed prices to retain customers.
“A weakened U.S. economy plus a supply glut at sea? That’s a recipe for brutal rate wars, idle tonnage, and carriers scrambling to plug financial holes,” said Jon Monroe, an industry consultant and former shipping executive. “The question isn’t if the storm hits, it’s how hard.”
Carriers had already begun reporting losses in late 2023, before Houthi attacks in the Red Sea forced vessel rerouting that temporarily absorbed excess capacity and lifted rates. With Red Sea disruptions now easing, freight prices from Asia to both U.S. coasts are once again approaching pre-crisis levels, said Peter Sand, Chief Analyst at Xeneta.
To mitigate losses, carriers are reportedly reducing capacity through measures such as blank sailings, slower steaming, port call cancellations, and scrapping older ships.
Despite these efforts, Jefferies’ Nokta predicts that Q4 2025 could be the weakest quarter for the industry since 2023.
“The tables are now turning in favor of shippers as they prepare for the next round of contract negotiations,” Sand said.
Reporting by Lisa Baertlein in Los Angeles; Editing by Nick Zieminski
© Reuters — All rights reserved under the Thomson Reuters Trust Principles.